Just when you thought you had the tax code figured out, it’s time to get acquainted with another round of changes. And speaking of changes, the 2027 Social Security inflation adjustments have been announced. In this month’s newsletter, we explore new tax rules for 2026, including several provisions of the One Big Beautiful Bill Act of 2025, and what the latest Social Security adjustments could mean for you.
What’s New in 2026? Tax Changes You Should Know About
Here are several important tax law changes worth knowing about before filing your 2026 return:
- New charitable contribution deductions. Even if you take the standard deduction, you can now deduct up to $1,000 in qualifying cash donations, or $2,000 for married couples filing jointly. If you itemize, charitable deductions are generally limited to contributions exceeding 0.5% of your adjusted gross income (AGI). Taxpayers in the highest bracket also face a 35% cap on the tax benefit of itemized deductions.
- Expanded 529 education savings benefits. Families can now withdraw up to $20,000 annually per beneficiary for qualifying K–12 education expenses, twice the previous $10,000 limit. Additional educational expenses also qualify for tax-free withdrawals.
- New Trump Accounts for children. Eligible children born from 2025 and 2028 can receive a one-time $1,000 federal contribution to a new tax-advantaged savings account. Families and other eligible contributors can generally add up to $5,000 annually.
- Increased dependent care benefits. If your employer offers dependent care benefits, you can now set aside up to $7,500 tax-free for qualifying expenses, up from $5,000. The Child and Dependent Care Credit also becomes more generous, with the maximum credit rate increasing from 35% to 50%, depending on income.
- Expanded Health Savings Account eligibility. Certain bronze and catastrophic health insurance plans now qualify for Health Savings Account (HSA) purposes. Qualifying direct primary care arrangements are also permitted without jeopardizing HSA eligibility.
- New limits on gambling loss deductions. Taxpayers can deduct only 90% of otherwise eligible gambling losses, up to the amount of their winnings. That means you could owe taxes even if your gambling winnings and losses break even.
- Additional tax breaks for educators. Eligible teachers and other educators who itemize can now deduct qualifying unreimbursed classroom expenses without the $300 limit that applies to the separate educator expense deduction. The same expenses cannot be deducted twice.
- New Roth catch-up contribution requirements. If you’re age 50 or older and earned more than $150,000 from your employer in the previous year, catch-up contributions to your employer-sponsored retirement plan generally must be made on a Roth (after-tax) basis. This change comes from the SECURE 2.0 Act.
- Expanded cryptocurrency reporting. Cryptocurrency brokers must now report cost basis for certain covered digital asset transactions on Form 1099-DA, making it easier for taxpayers and the IRS to track gains and losses. The reporting requirements stem from legislation passed in 2021.
- Higher estate and gift tax exemption. The federal estate and gift tax exemption increases to $15 million per person, or $30 million for married couples through proper planning, giving families more flexibility to transfer wealth without triggering federal estate or gift taxes.
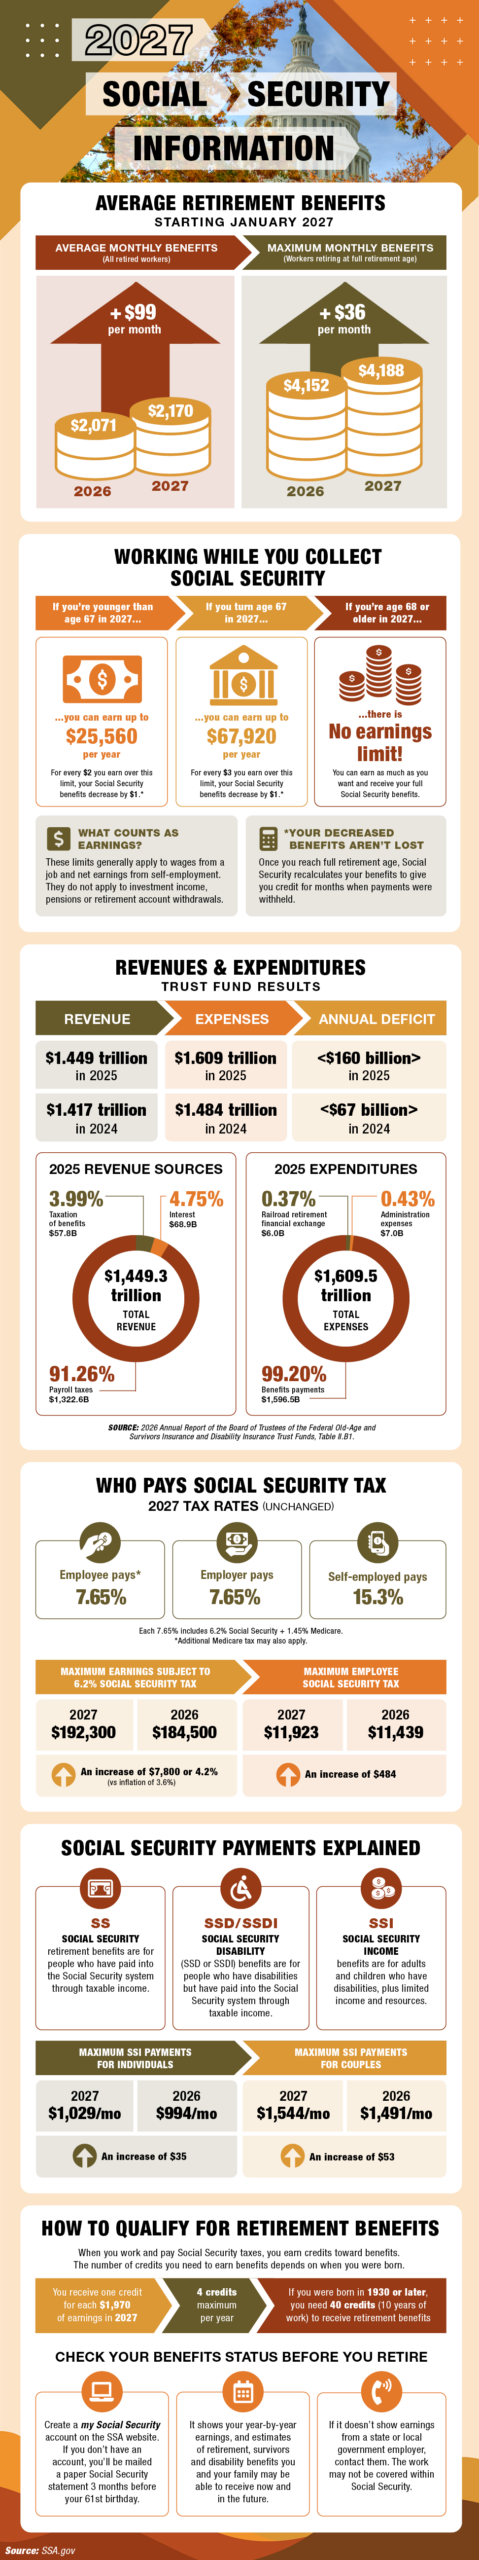
2027 Social Security Changes Announced
The Bills You Should Renegotiate Every Year
Many household bills gradually increase over time, often without much notice. Taking a little time each year to review your expenses, compare prices, and negotiate better rates could save you hundreds of dollars. Here are several bills to consider revisiting annually.
- Insurance. Compare rates for auto, homeowner’s and renters insurance periodically. Even if you don’t switch, competing quotes give you a reference point. Also ask your current insurer about discounts, deductibles and whether your coverage still fits your needs.
- Internet. Longtime customers can wind up paying more than newer customers when promotional pricing expires. Check competitors’ current offers, then ask your provider whether there are less expensive plans or retention offers available.
- Cell phone service. Don’t assume the plan you’ve had for five years is still the best plan for your family. Review how much data you’re actually using, whether you’re paying for unused lines or features, and what competing carriers offer.
- Subscriptions and memberships. Streaming services, software, gyms, satellite radio, security systems and other recurring services may have cheaper tiers or retention offers. Even when they won’t negotiate, you can downgrade or cancel.
- Bank services. Your bank may offer better rates or lower fees than those it advertises. Depending on the bank and your relationship with it, you may be able to ask for a higher rate on a savings account, money market account or CD, particularly if you’re considering moving a sizable balance elsewhere. Banks may also have some flexibility with credit card annual fees, certain account fees and, in some cases, loan or credit card interest rates. Before automatically accepting the rate you’re earning or paying, see what competitors are offering and ask your bank whether it can match or improve upon it.
Tips to renegotiate
- Do a few minutes of homework. Don’t call and simply ask for a discount. Know what you’re currently paying. Look up what the company is offering new customers. Check one or two competitors. Then call with something specific: I’m paying $145 a month now, and I’m seeing comparable service for around $100. Are there any plans or discounts available that could lower my bill?
- Ask what options are available, not just whether they can lower the price. A representative may not be able to simply knock $20 off your bill, but they may be able to move you to a different plan, apply a promotion, remove a fee or offer a loyalty discount. Try asking, Are there any other plans, promotions or discounts available that could lower what I’m paying?
- Be willing to walk away, or at least know your alternatives. Your strongest negotiating position is knowing you have another option. If the company can’t improve the price, politely ask what you need to do to cancel or switch. You don’t have to threaten to leave, and you shouldn’t bluff. But if a competitor offers comparable service for substantially less, being prepared to switch gives you a meaningful alternative.
Things We Used to Do All the Time – and Why They Might Be Worth Bringing Back
Some of life’s simplest pleasures can be found in everyday habits we might have taken for granted. As technology and convenience change the way we live, perhaps it’s worth taking another look at a few traditions that might deserve a comeback.
- The lost art of knowing your neighbors. Knowing the people next door, borrowing a ladder, watching someone’s house, kids playing together, neighborhood conversations in the driveway.
- Eating dinner together. Not necessarily every night, but having a regular meal where everyone is actually in the same place without screens competing for attention.
- Calling someone just to talk. Before texting, a phone call didn’t necessarily require a reason. You called someone because you hadn’t talked to them lately.
- Dropping by without an appointment. This one has changed dramatically. Showing up at a friend or relative’s house used to be fairly normal. Today it can feel almost socially unacceptable.
- Letting kids figure out what to do. Going outside, finding other kids and inventing something to do rather than having every hour organized around activities.
- Fixing things before replacing them. Clothes were mended, appliances repaired and furniture refinished. Now replacement can sometimes be easier than repair.
- Asking people instead of looking it up. Directions, recipes, recommendations, advice and random facts once created little human interactions that Google eliminated.
- Writing things down. Grocery lists, calendars, phone numbers, recipes, notes and even letters. There could be an interesting distinction between writing something down and simply storing it somewhere digitally.
- Having a few hours when nobody can reach you. Before smartphones, being unavailable wasn’t unusual. You went somewhere and people simply waited until you came home.
- Taking pictures without immediately sharing them. Photos primarily existed to preserve a memory rather than communicate what you were doing right now.
- Memorizing actual phone numbers. Almost everyone once knew dozens of them. Now many people might struggle to give you more than a handful.
- Making something from scratch. Cooking, woodworking, sewing, gardening, crafts and other activities that were once ordinary household skills rather than hobbies.
- Passing down family stories. Stories about grandparents, childhoods, family characters and “the time your dad…” were often transmitted simply because families spent time talking.
Thoughtful Action Plan
- Reflect on what matters. Think about the everyday traditions you remember most fondly. What made them meaningful, and could they still enrich your life today?
- Choose what works for you. Not every old habit deserves a comeback. Focus on the ones that fit your lifestyle and bring genuine enjoyment or connection.
- Make room for the good stuff. Sometimes improving your life isn’t about adding something new. It’s about making more time for the simple things that have always mattered.